An income tax calculator helps them estimate that gap quickly. It does not replace advice, but it can clarify what they might keep, what they might owe, and what needs deeper planning.
What is an income tax calculator in Australia used for by investors?
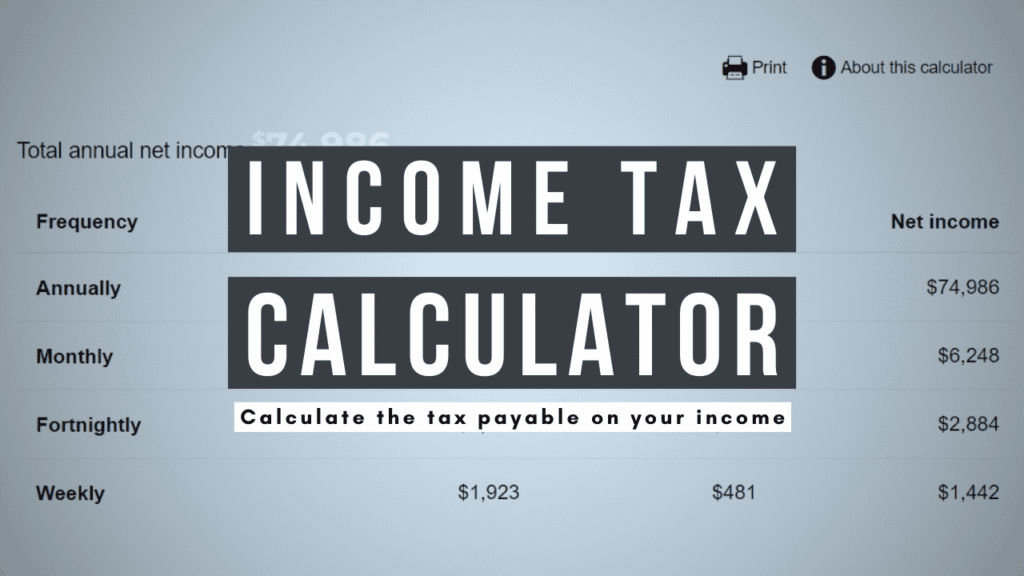
Investors use an income tax calculator to estimate their tax payable and net income after adding investment income to their other earnings. In practice, they plug in salary, deductions, and extra income like interest, dividends, or rent to see the change in tax and take-home pay.
This is most useful for comparing scenarios. For example, they can test how a higher yield, extra deductible costs, or a different holding structure might shift the after-tax result.
Which numbers should investors gather before using a calculator?
hey get the best estimate when they start with accurate inputs. Using an income tax calculator Australia, they typically collect their taxable income details and the investment’s expected cash flow, plus the most common offsets and deductions.
Key numbers to have ready include salary or business income, other taxable income, expected interest or dividends, rental income and expenses, super contributions, work-related deductions, private health cover status, and any carried-forward capital losses.
How do investors estimate after-tax returns from interest income?
Interest is usually taxed at their marginal tax rate, so it can be one of the simplest calculations. They estimate annual interest, add it to their taxable income, and use the calculator to see the additional tax.
Their after-tax interest is roughly: interest received minus the extra tax triggered by that interest. Investors also sanity-check that the “extra tax” reflects their bracket and Medicare levy assumptions.
How do investors estimate after-tax returns from dividends?
Dividends can be straightforward or complex depending on franking. Investors separate the cash dividend from any franking credits and then model both, because the tax outcome depends on their marginal rate.
With fully franked dividends, they often add the “grossed-up” dividend to taxable income and then apply the franking credit as a tax offset. The calculator helps estimate whether they may pay top-up tax or potentially receive a refund of unused credits.
How do investors estimate after-tax returns from rental property?
For property, investors focus on net rental income, not gross rent. They estimate rent received for the year and subtract deductible expenses such as interest (if applicable), property management fees, insurance, repairs, and depreciation (where relevant).
They then add the resulting net figure to taxable income. If the property is negatively geared, the calculator shows the potential tax reduction, which effectively increases the after-tax outcome even if cash flow is negative.
How do they account for capital gains tax in after-tax estimates?
Capital gains are not taxed like regular income line-by-line, but they still feed into taxable income in the year of sale. Investors estimate the capital gain as sale price minus cost base (including eligible costs), then apply any capital losses.
If they held the asset for more than 12 months, individuals and trusts may use the 50% CGT discount. They then add the discounted gain to taxable income and use the calculator to estimate the extra tax for that year.
What does the Medicare levy and Medicare levy surcharge change?
The Medicare levy is generally an additional percentage on taxable income, so investors include it when comparing after-tax outcomes. Many calculators include it by default, but it depends on residency, income, and certain exemptions.
The Medicare levy surcharge can apply if they earn above thresholds and do not have appropriate private patient hospital cover. For investors, this matters because extra investment income might push them over a threshold, raising the effective tax on the next dollar earned.
How do deductions and offsets affect the “real” after-tax return?
Deductions reduce taxable income, which can reduce tax at their marginal rate. Offsets reduce tax payable directly, which can be more valuable dollar-for-dollar, depending on eligibility.
Investors often test deductions like interest on investment loans (where deductible), accounting fees, and certain holding costs. They also consider offsets such as franking credits, and where applicable, other tax offsets that may be income-tested.
How do investors compare two investments using a calculator?
They run both investments through the same personal income baseline. First, they estimate tax without the investment, then estimate tax with the investment income included, and treat the difference as the tax impact of that investment.
They then compute an after-tax return using net income kept divided by the amount invested. This makes comparisons fair across different income types, like interest versus franked dividends versus a capital-gains-heavy asset.
What mistakes do investors commonly make when using tax calculators?
They often confuse cash flow with taxable income. Rental depreciation can reduce taxable income without changing cash in hand, while capital gains may create tax without providing liquidity unless proceeds are set aside.
They also forget timing. A CGT bill hits in the financial year of disposal, while distributions, dividends, and interest may be received at different times. Investors should treat calculator outputs as annualised estimates, not cash planning tools.
When should they treat the results as “rough only” and get advice?
They should be cautious when structures, residency, or complex income is involved. Trust distributions, company structures, foreign income, carried-forward losses, and Division 293 or concessional contribution issues can shift outcomes materially.
They also seek advice when planning a sale that triggers CGT, when starting or stopping negative gearing, or when their income is near Medicare levy surcharge thresholds. A calculator is a quick estimate, but strategy needs confirmation.
What’s a simple step-by-step method they can follow to estimate after-tax returns?
They can keep it simple and repeatable. The goal is to isolate the incremental tax caused by the investment and compare that with the pre-tax return.
- Estimate baseline taxable income and deductions for the year.
- Run the calculator and note estimated tax payable.
- Add expected investment income (or net rental income, or discounted capital gain).
- Re-run the calculator and note the new estimated tax payable.
- The difference is the investment’s estimated tax impact.
- After-tax profit is investment cash flow minus that extra tax.
- After-tax return is after-tax profit divided by invested amount.
What should investors do next after they get an after-tax estimate?
They should stress-test the result with a few scenarios, such as a higher income year, lower income year, higher interest rates, vacancy, or a different sale date. Small changes can shift marginal rates and alter the real return.
If the estimate materially affects a decision, they typically validate assumptions with an accountant or tax adviser. The calculator helps them ask better questions, but it should not be the only input into an investment decision.
FAQs (Frequently Asked Questions)
What is the purpose of an income tax calculator for investors in Australia?
An income tax calculator helps Australian investors estimate their tax payable and net income after factoring in investment income alongside other earnings. It allows them to input salary, deductions, and additional income such as interest, dividends, or rent to compare different investment scenarios and understand potential after-tax outcomes quickly.
Which financial details should investors prepare before using an Australian income tax calculator?
Investors should gather accurate information including their taxable income details like salary or business income, other taxable earnings, expected interest or dividends, rental income and expenses, super contributions, work-related deductions, private health cover status, and any carried-forward capital losses to obtain precise estimates from the calculator.
How do investors calculate after-tax returns from dividends using a tax calculator?
Investors separate cash dividends from franking credits and model both since tax outcomes depend on their marginal rate. For fully franked dividends, they add the grossed-up dividend to taxable income and apply the franking credit as a tax offset. The calculator then estimates if top-up tax is owed or if a refund of unused credits is possible.
How can investors estimate after-tax returns from rental properties with an income tax calculator?
Investors focus on net rental income by subtracting deductible expenses such as interest, property management fees, insurance, repairs, and depreciation from gross rent received. This net figure is added to taxable income. If negatively geared, the calculator shows potential tax reductions that effectively improve after-tax returns despite negative cash flow.
What role does capital gains tax (CGT) play in after-tax investment return calculations?
Capital gains are included in taxable income in the year of sale. Investors estimate gains by subtracting cost base from sale price and applying any capital losses. For assets held over 12 months, a 50% CGT discount may apply. Adding this discounted gain to taxable income allows the calculator to estimate additional tax payable that year.
Why should investors consider Medicare levy and surcharge when calculating after-tax returns?
The Medicare levy adds an extra percentage on taxable income and is usually included by default in calculators. The Medicare levy surcharge applies if earnings exceed certain thresholds without appropriate private hospital cover. Additional investment income can push taxpayers over these thresholds, increasing effective tax rates on subsequent earnings. For a clearer view of lending structures and bank assessment nuances, see how investment property loans for doctors are structured and the key factors lenders may not always highlight upfront.